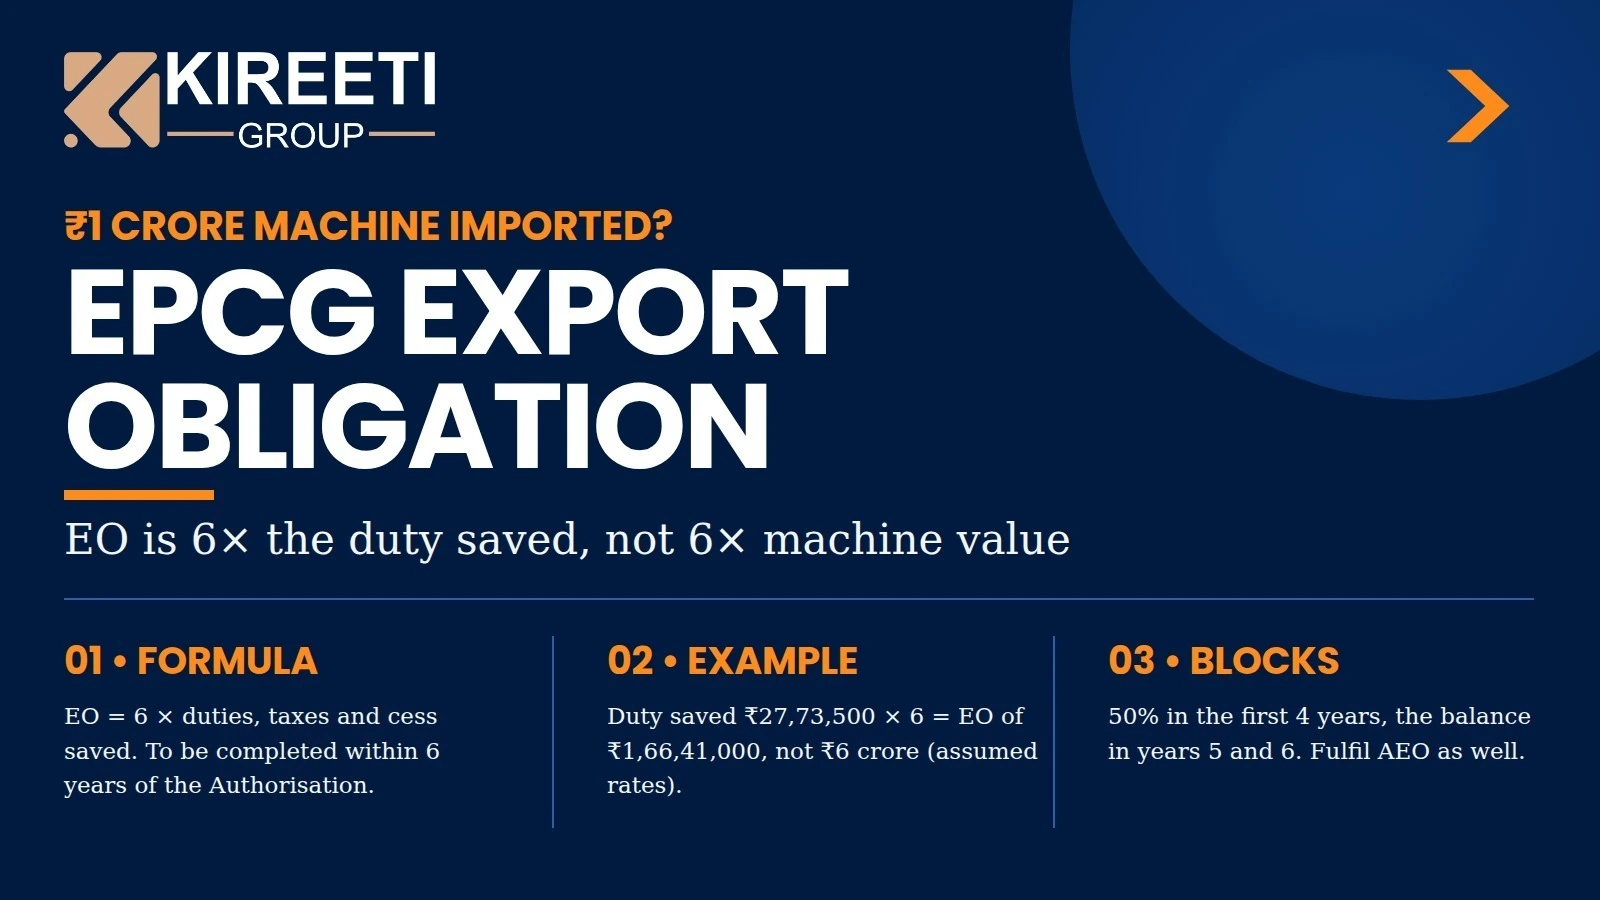
Imported a machine worth ₹1 crore under EPCG and want to know how much you need to export? The Export Obligation (EO) is 6 times the duties, taxes and cess saved, not 6 times the machine's value. So it does not automatically mean you must export ₹6 crore. Let us see how to calculate the EO with an example, and the cases where your EO changes.
Quick Facts
| Particular | Key Information |
|---|---|
| EO formula | EO is 6 times the duties, taxes and cess saved on the capital goods. It must be completed within 6 years from the date the Authorisation is issued (FTP 2023, Para 5.01(b)). |
| Direct imports | For directly imported machinery, EO is calculated using the actual duties, taxes and cess saved (FTP 2023, Para 5.08). |
| Buying in India | If you buy machinery from an Indian supplier, EO is based on the notional duties, taxes and cess saved on the FOR value shown in the ARO or Invalidation Letter (FTP 2023, Para 5.08). |
| Block-wise EO | You must complete 50% of the specific EO in the first 4 years and the balance in years 5 and 6 (HBP 2023, Para 5.13). |
| Average Export Obligation (AEO) | You also need to fulfil the Average Export Obligation (AEO) in addition to the specific Export Obligation. Only exports over and above the AEO are counted towards the specific EO (FTP 2023, Para 5.04(c)). |
Scroll left to see the full table
The EO Formula in 3 Simple Steps
- Find the duty saved: Calculate the total duties, taxes and cess saved on import, including applicable BCD, SWS, IGST and Compensation Cess, as per EPCG rules.
- Multiply by 6: The result is your specific EO.
- Split the EO into blocks: Fulfil 50% of the EO in the first 4 years and the remaining 50% in years 5 and 6.
Example: ₹1 Crore Machine – EO Calculation
Suppose a manufacturer imports an eligible machine with a Customs assessable value of ₹1,00,00,000. Assume the applicable EPCG exemptions are available and claimed. The rates are assumed for illustration only; actual rates depend on your machine's HS code and any related notifications.
| Particulars | Rate × Base | Amount |
|---|---|---|
| Basic Customs Duty | 7.5% × ₹1,00,00,000 | ₹7,50,000 |
| Social Welfare Surcharge | 10% × ₹7,50,000 | ₹75,000 |
| IGST | 18% × ₹1,08,25,000 (assessable value + BCD + SWS) | ₹19,48,500 |
| Total duties, taxes and cess saved | — | ₹27,73,500 |
| Export Obligation | 6 × ₹27,73,500 | ₹1,66,41,000 |
| First block (years 1 to 4) | 50% × ₹1,66,41,000 | ₹83,20,500 |
| Balance (years 5 and 6) | ₹1,66,41,000 − ₹83,20,500 | ₹83,20,500 |
Scroll left to see the full table
The EO is fulfilled based on the FOB value of eligible exports, as per EPCG rules. In this example, the specific EO is ₹1,66,41,000. The amount will change depending on the duties, taxes and cess you saved on your imports.
Can Your EO Be Lower?
In some cases, your specific EO can be reduced, or you may not need to complete the remaining EO. Only one of these benefits can be claimed (FTP 2023, Para 5.04(l)).
When the specific EO may be reduced
- Capital goods bought in India under EPCG: Specific EO is reduced by 25%.
- Eligible green technology products: Specific EO is reduced by 25%.
- Eligible units in the North-Eastern States, Jammu & Kashmir and Ladakh: Specific EO is reduced by 75%.
- Early fulfilment: If you complete at least 75% of your specific EO, along with 100% of the AEO till date, within half of your original EO period, you are not required to fulfil the remaining specific EO (FTP 2023, Para 5.09).
Mistakes to Avoid
- Using the machine value: Calculate EO on the duties, taxes and cess saved, not on the machine value.
- Forgetting the AEO: You must also meet the Average Export Obligation, where applicable.
- Ignoring the IGST rule: If you have paid IGST and Compensation Cess in cash and not claimed ITC, these are not included in the duty saved (FTP 2023, Para 5.01(e)).
- Missing the block deadline: You must complete 50% of the specific EO in the first 4 years and the balance in years 5 and 6. Make sure you meet these deadlines.
What to Do Next
- Check the duty saved amount shown in your Authorisation.
- Calculate the required EO and the amount to be completed in each block.
- Plan your exports to meet the target within the first 4 years, and the remaining EO in years 5 and 6.
- Submit EO reports online as required. After completing the EO, apply for EODC in ANF 5B. Once the EODC is issued, your Authorisation is closed.
Why Kireeti Group
Before importing machinery under EPCG, you should know how much Export Obligation you will need to fulfil later. This helps you plan your exports and avoid problems later. Kireeti Group can help you with:
- Checking how much duty can be saved before you import.
- Calculating your total EO and block-wise targets.
- Tracking your exports and Average Export Obligation (AEO).
- EO reports and EODC filing for closure.
Planning to import machinery under EPCG? Talk to Kireeti Group before you apply.
Official Sources
- Chapter 5 of Foreign Trade Policy (FTP) 2023.
- Chapter 5 of Handbook of Procedures (HBP) 2023, as amended.
- Customs Notification No. 26/2023-Customs dated 1st April 2023.
- DGFT Public Notice No. 24/2024-25 dated 20th September 2024.