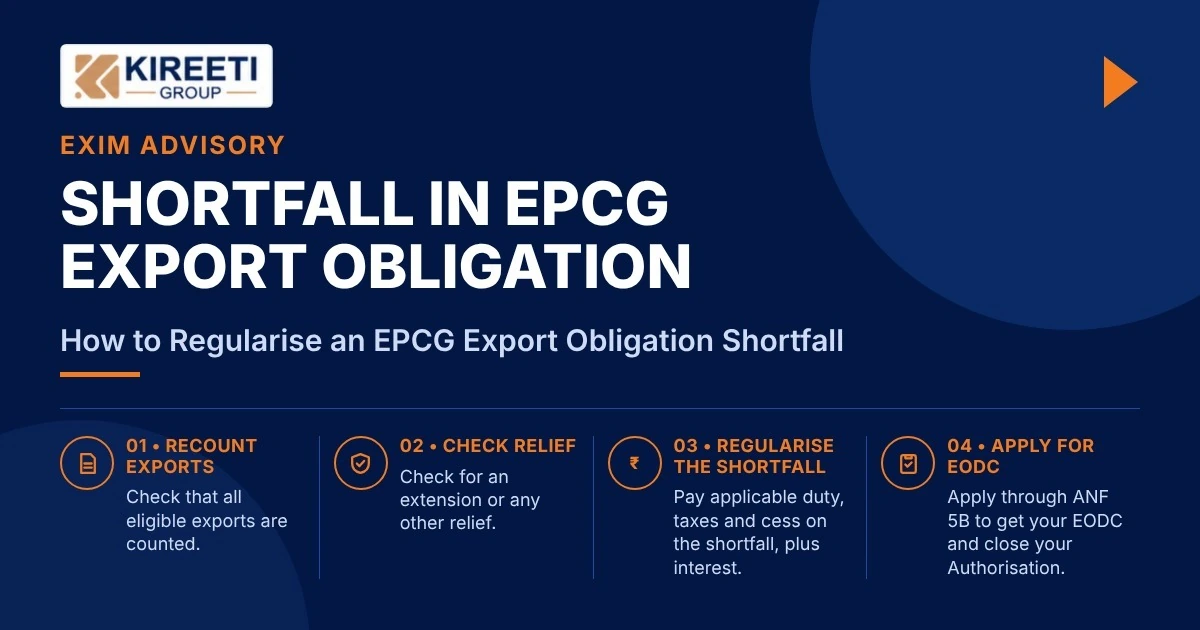
Do not ignore a shortfall in your EPCG Export Obligation (EO) if it is not completed. First, make sure that all eligible exports are counted. Then determine whether there is an extension or any relief. If there is still a shortfall, it may be regularised by paying customs duty, taxes and cess proportionate to the shortfall, along with interest as prescribed by the Customs Authority. The amount payable is calculated in proportion to the EO shortfall, rather than on the entire duty saved under the Authorisation.
Quick Facts
| Particular | Key Information |
|---|---|
| EPCG basics | |
| Export Obligation | EO is 6 times the duties, taxes and cess saved, which must be fulfilled within 6 years from the date of issue of the EPCG Authorisation. 50% of the specific EO must be completed in the first 4 years, and the balance in years 5 and 6 (FTP 2023, Para 5.01(b); HBP 2023, Para 5.13). |
| If you have a shortfall | |
| How to regularise | If EO falls short, customs duty, taxes and cess are charged based on the shortfall in EO, and interest is charged at the rate prescribed by the Customs Authority (HBP 2023, Para 5.21(b)). |
| Extension first | The RA may grant an extension of the first block under HBP 2023, Para 5.13(c). Two extensions of 1 year each, or one extension of 2 years, may be added after 6 years with a composition fee, for a total of 8 years maximum (Para 5.16(b)(c)). |
| Export ban | If your export product is banned or restricted, the EO period may be extended automatically for the period of the ban, subject to the conditions in HBP 2023, Para 5.19. |
Scroll left to see the full table
Before You Pay: Recount Your Export Obligation
Before calculating the shortfall, check that all eligible exports have been correctly counted towards the Authorisation, after applying the applicable Average Export Obligation (AEO) conditions. Where AEO applies, exports or supplies made over and above the required AEO are counted towards the specific EO (FTP 2023, Para 5.04(c)).
What may count towards the EO
- Goods you or your supporting manufacturer have exported, and services you have provided.
- Exports made through a third party, if you have the required documents.
- Exports under Advance Authorisation, DFIA, Duty Drawback, RoSCTL and RoDTEP, and deemed exports.
- Any other exports, supplies or receipts allowed under EPCG.
Be ready with shipping bills/invoices, along with an EO statement certified by a Chartered Accountant, Cost Accountant or Company Secretary (HBP 2023, Para 5.14), and proof of realisation. Export records should be kept for a period of 2 years from the redemption date (HBP 2023, Para 5.22).
How to Regularise the Shortfall
- Recount the eligible exports you have completed so far.
- Check whether any AEO relief or export-ban extension applies in your case.
- Check whether any extension is possible for the block or the EO period.
- If a shortfall still remains, calculate the proportionate duty, taxes and cess, and add the applicable interest.
- Make the payment and keep the payment proof.
Before paying duty and interest, exporters should verify that all eligible exports and supplies have been counted correctly. EPCG Compliance Consultants can help review export records and identify possible gaps in the Export Obligation calculation.
Example: ₹25 Lakh EO Shortfall
Let's say the duty saved under an EPCG Authorisation is ₹20,00,000. Assume that the 6-year EO period has expired, the exporter has achieved an eligible EO of ₹95,00,000, and the AEO has been met. These numbers are for illustration purposes only.
| Particulars | Calculation | Amount |
|---|---|---|
| Required EO | 6 × ₹20,00,000 (duty saved) | ₹1,20,00,000 |
| Eligible EO completed | — | ₹95,00,000 |
| EO shortfall | ₹1,20,00,000 − ₹95,00,000 | ₹25,00,000 |
| Proportionate duty, taxes and cess | ₹20,00,000 × (₹25,00,000 ÷ ₹1,20,00,000) | ₹4,16,667 |
Scroll left to see the full table
What Does This Mean?
The EO shortfall is ₹25,00,000. The proportionate duty, taxes and cess to be paid is ₹4,16,667 (approx. 21% of the duty saved), plus interest as determined by the Customs Authority.
What Happens Next?
- Pay duty, taxes and cess proportionate to the shortfall, along with interest.
- Submit the EO report online (HBP 2023, Para 5.14).
- Apply for the EODC in ANF 5B (HBP 2023, Para 5.20). Once you receive the EODC, your Authorisation is closed.
Why Kireeti Group
Before you make any payment for your EPCG shortfall, first check how many options are available. A wrong calculation or a missed deadline can increase your cost. Kireeti Group will help you with:
- Checking your eligible exports.
- Calculating the shortfall, if any, along with duty and interest.
- Checking extension or relief options, if available in your case.
- Helping you with payment and EODC filing for closure of the Authorisation.
Having an EPCG shortfall? Talk to Kireeti Group before you make the payment.
Official Sources
- Foreign Trade Policy 2023, Chapter 5
- Handbook of Procedures 2023, Chapter 5